By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
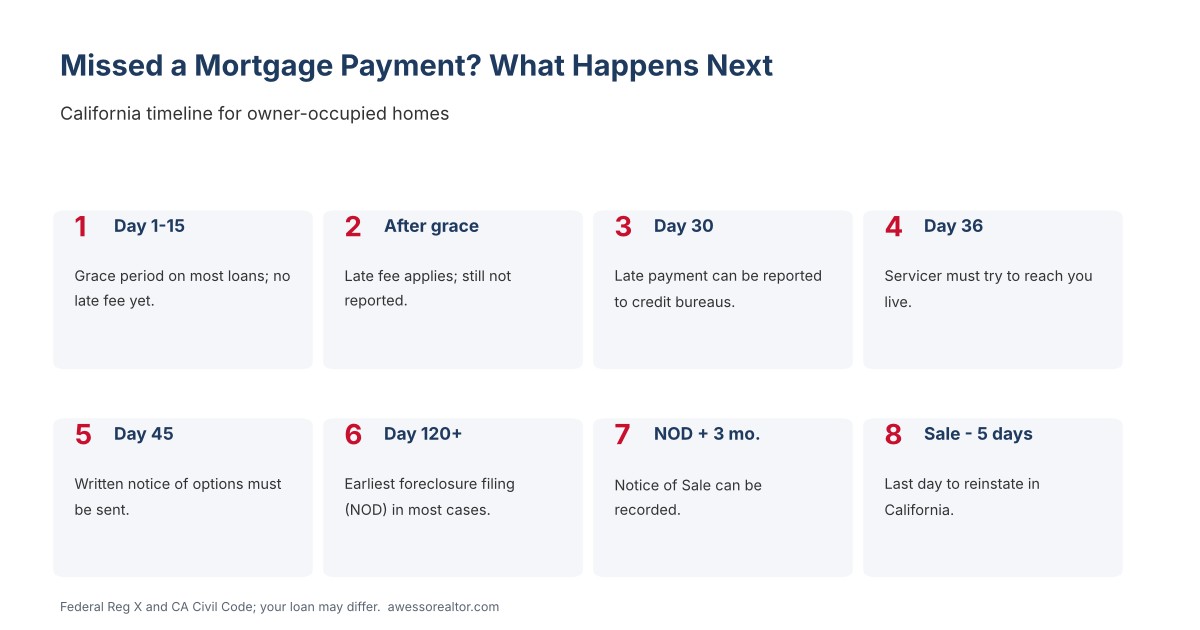
Quick answer: If you miss a mortgage payment in California, you'll usually owe a late fee after the grace period (often 15 days), and the late payment can be reported to the credit bureaus once you're 30 days behind. Your servicer must try to contact you by day 36 and send written information about options by day 45. Under federal rules, a servicer generally can't start foreclosure until you're more than 120 days behind. In California, that first step is a recorded Notice of Default, followed by at least three months before a Notice of Sale. You have options at every stage, and acting in the first month gives you the most.
The First 30 Days
- Grace period: most mortgages give you about 15 days after the due date before a late fee applies. Check your note or statement.
- Late fee: often a percentage of the overdue principal and interest. California limits late charges on many home loans.
- No credit report yet: servicers generally report a payment as late only once it's 30 days past due.
If you can pay within the month, do it, even with the late fee. A payment made before 30 days usually doesn't show up as late on your credit report.
Days 30 to 45: Your Servicer Must Reach Out
Federal mortgage servicing rules (Regulation X) require early intervention:
- By day 36: the servicer must make good-faith efforts to reach you live, by phone or in person, and tell you about loss mitigation options if appropriate.
- By day 45: it must send a written notice explaining options, how to apply, and how to reach a housing counselor.
Don't wait for the call. Phone your servicer yourself, explain what happened, and ask for a loss mitigation application. Read how to talk to your mortgage servicer.
Days 45 to 120: The Window to Fix It
This is the most important stretch. You're behind, but foreclosure can't legally start yet in most cases. Use it to:
- Submit a complete loss mitigation application with every document the servicer requests.
- Ask about forbearance, a repayment plan, a loan modification, or a partial claim for FHA and VA loans. Compare them in forbearance vs. repayment plan vs. modification.
- Talk to a free HUD-approved housing counselor.
- Get a home value estimate so you know whether selling is a realistic backup.
If you submit a complete application before the servicer starts foreclosure, federal rules generally prevent it from making the first foreclosure filing while your application is being reviewed.
After 120 Days: How California Foreclosure Works
Most California foreclosures are nonjudicial, meaning they don't go through court. The key steps:
| Step |
What happens |
Timing |
| Pre-foreclosure outreach |
Servicer must contact you to assess your finances and explain options |
At least 30 days before the Notice of Default |
| Notice of Default (NOD) |
Recorded with the county |
Usually after 120+ days delinquent |
| Waiting period |
You can still reinstate, apply for help or sell |
At least 3 months |
| Notice of Trustee Sale |
Sets the auction date |
At least 20 days before the sale |
| Reinstatement deadline |
Pay past-due amounts and fees to stop the sale |
Up to 5 business days before the sale |
| Trustee sale |
The home is auctioned |
Postponements are common |
California's Homeowner Bill of Rights also generally limits "dual tracking" for owner-occupants, so a servicer usually can't move to sale while a complete first-lien modification application is pending.
What a Missed Payment Does to Your Credit
- One 30-day late payment can lower your score noticeably, especially if your credit was strong.
- Each additional month (60, 90, 120 days late) adds more damage.
- A foreclosure stays on your credit report for about seven years.
- A completed loan modification, repayment plan or sale while current usually does far less long-term harm than a foreclosure.
Your Options at Each Stage
| Stage |
Best options |
| Missed one payment |
Catch up, or call the servicer about a short repayment plan |
| Two to three months behind |
Repayment plan, forbearance, modification, partial claim |
| Notice of Default recorded |
Modification, reinstatement, sale, short sale |
| Notice of Sale recorded |
Reinstate by the deadline, sale or short sale if time allows, talk to an attorney |
Selling as a Backup Plan
If you have equity, selling before the trustee sale lets you pay off the loan and keep what's left. If you owe more than the home is worth, a short sale may be possible with lender approval. The earlier you list, the better your price. Get a free home value estimate or read your options in California.
Special Protections for Military Homeowners
The Servicemembers Civil Relief Act (SCRA) can limit foreclosure on mortgages taken out before active duty, and can cap interest at 6% on those loans. Tell your servicer you're on active duty and contact your base legal assistance office.
Watch for Scams
When a Notice of Default is recorded, it's public. Expect letters and calls from people offering to "save" your home. Never pay upfront fees for loan modification help, never sign over your deed, and only work with your servicer, a HUD-approved counselor, a licensed attorney or a licensed real estate professional.
Related Guides
Frequently Asked Questions
How long before my lender forecloses in California?
Federal rules generally prevent a foreclosure filing until you're more than 120 days behind. California then requires at least three months between the Notice of Default and the Notice of Sale, plus at least 20 days' notice before the sale.
Will one missed payment hurt my credit?
If you pay before it's 30 days late, it usually isn't reported. Once it's 30 days past due, it can be reported and lower your score.
Can I stop foreclosure by paying what I owe?
Yes. In California you can usually reinstate the loan by paying the past-due amount, fees and costs up to five business days before the trustee sale.
Who can I talk to for free help?
A HUD-approved housing counselor, found through the CFPB counselor search, and your servicer's loss mitigation department.
Behind on a Payment?
Call or text me at 951-282-7007 for a confidential talk about your home's value and your options. No pressure, no judgment.
#MissedMortgagePayment #ForeclosurePrevention #MortgageHelp #California #RiversideCounty #Murrieta #Temecula #Homeowners #LoanModification #SCRA #HousingCounselor
Sources: 12 CFR §§ 1024.39 and 1024.41 (Regulation X early intervention and loss mitigation); California Civil Code §§ 2923.5, 2923.6, 2924 and 2924c; Consumer Financial Protection Bureau; Servicemembers Civil Relief Act. Timelines depend on your loan and circumstances. This article is general information, not legal, tax or financial advice. Talk to a HUD-approved housing counselor or an attorney about your situation.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now