By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: When you call your mortgage servicer, say clearly that you're having a hardship, that you want to keep your home if possible, and that you want a loss mitigation application. Ask what options exist for your loan type, what documents they need and by when, and who your single point of contact is. Write down every name, date and answer, send documents in a way you can track, and follow up in writing. A complete application gives you the most protection.
Who Is Your Mortgage Servicer?
Your servicer is the company that collects your payments. It may not be the lender that made your loan. You'll find its name, phone number and mailing address on your monthly statement. Loans are often transferred to new servicers, and you should get a notice when that happens.
Before You Call: Get Ready
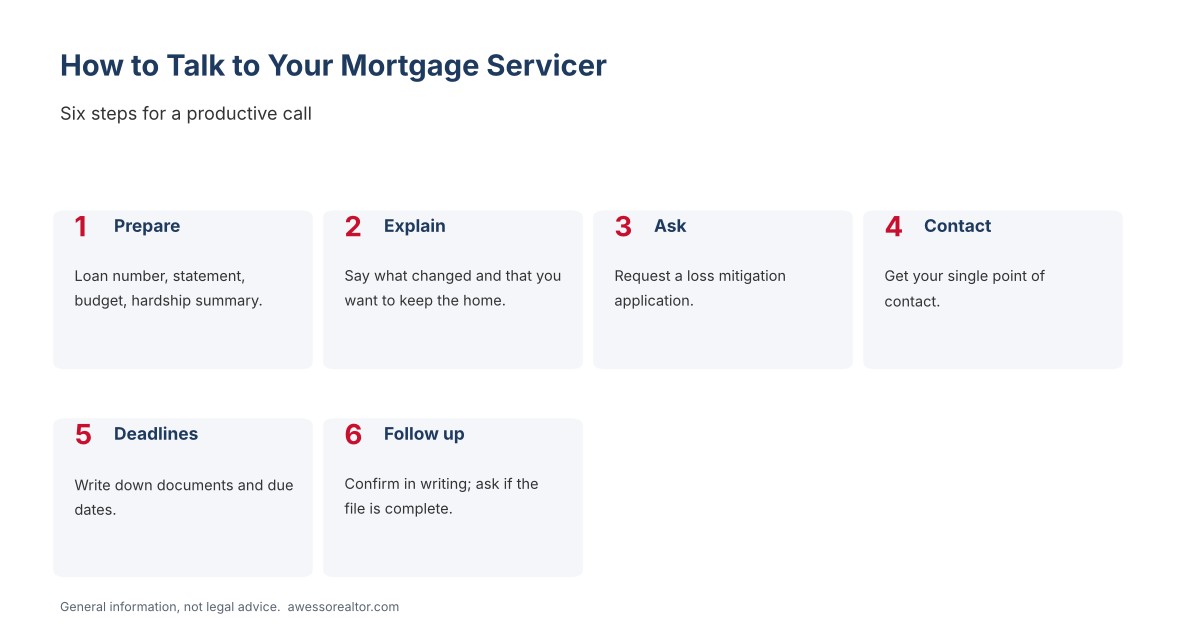
- Your loan number and the last four digits of your Social Security number
- Your most recent mortgage statement
- A simple monthly budget: income, expenses, other debts
- A short explanation of what changed and when (job loss, illness, divorce, higher escrow, deployment)
- Something to take notes with
What to Say
Keep it simple and factual. You can use this script:
"Hi, my name is ___ and my loan number is ___. I'm having trouble making my payments because ___. I want to keep my home if possible. Please send me a loss mitigation application and tell me which options I may qualify for. Who will be my single point of contact?"
Be honest about your income and what you can afford. Servicers look at whether a solution is sustainable.
Questions to Ask
- What loss mitigation options are available for my loan type (conventional, FHA, VA, USDA)?
- What documents do you need, and what's the deadline?
- Where and how should I send them?
- Who is my single point of contact, and what's their direct line?
- Is my account being referred to foreclosure? If so, when?
- How will each option be reported to the credit bureaus?
- Will late fees be waived if I enter a plan?
- If my payment went up, can you send me the escrow analysis?
What to Ask For, by Situation
| Your situation |
Ask about |
| Temporary hardship, income coming back soon |
Forbearance, then a repayment plan, deferral or partial claim |
| Behind a few months, can now pay a bit extra |
Repayment plan |
| Permanent drop in income |
Loan modification |
| FHA or VA loan |
Partial claim (moves arrears into a separate, deferred balance) |
| Payment rose because of escrow |
Escrow analysis review and spreading the shortage |
| Can't afford the home long term |
Short sale or deed in lieu, and time to sell |
Learn the differences in forbearance vs. repayment plan vs. loan modification.
Your Rights When Dealing With a Servicer
- Single point of contact: California's Homeowner Bill of Rights requires servicers to give many owner-occupants a single point of contact during loss mitigation.
- Timely review: under federal rules, if you send a complete application more than 37 days before a scheduled foreclosure sale, the servicer generally must evaluate you for all options within 30 days and tell you the result in writing.
- Appeals: if you're denied a modification, you may have the right to appeal in many cases. Ask about the deadline.
- Errors and information requests: you can send a written notice of error or request for information to the servicer's designated address. Servicers must acknowledge and respond within set timelines.
Document Everything
Keep a simple log for every call:
| Date |
Name / ID |
What they said |
Next step and deadline |
| |
|
|
|
Send documents through the servicer's portal, fax with confirmation, or certified mail. Keep copies of everything you send.
Common Mistakes to Avoid
- Sending an incomplete application. Ask, "Is my application complete?" and get the answer in writing.
- Missing a document deadline. Calendar every date the servicer gives you.
- Agreeing to a plan you can't afford. A failed plan leaves you worse off.
- Stopping payments because someone told you to. Never do that without advice from your servicer, a counselor or an attorney.
- Paying a company upfront to negotiate for you. Free help is available.
When to Bring in Help
A HUD-approved housing counselor can call the servicer with you, review your application and explain your options for free. Find one through the CFPB counselor search. If a sale date is set or you believe the servicer made an error, talk to a real estate attorney or legal aid.
Military Homeowners
Tell your servicer if you're on active duty, recently received PCS orders, or are deploying. You may have SCRA protections, and some servicers have military assistance teams. Your base legal assistance office can help.
Sample Follow-Up Letter
After important calls, send a short written follow-up so there's a record:
"On [date], I spoke with [name] about loan number [number]. I was told [summary]. I am submitting [documents] by [date]. Please confirm in writing whether my loss mitigation application is complete and let me know if anything else is needed."
Documents Servicers Usually Request
- Loss mitigation application form
- Hardship letter
- Two recent pay stubs or proof of other income
- Two years of tax returns or W-2s
- Two to three months of bank statements
- IRS Form 4506-C or similar tax transcript request
- For self-employed borrowers, a profit and loss statement
What to Do If You're Denied
- Ask for the denial reason in writing.
- Ask whether you can appeal, and the deadline.
- Check the income and expense numbers the servicer used for mistakes.
- Ask whether other options are available.
- Talk to a housing counselor or attorney if a sale date is close.
Related Guides
Frequently Asked Questions
What should I say when I call my mortgage company?
Explain your hardship briefly, say you want to keep your home if possible, and ask for a loss mitigation application and a single point of contact.
Will calling my servicer hurt my credit?
No. Calling doesn't affect your credit. Late payments and some loss mitigation options can be reported, so ask how each option is reported.
How long does the servicer have to review my application?
If your complete application arrives more than 37 days before a scheduled foreclosure sale, federal rules generally require a decision within 30 days.
Who can help me talk to my servicer for free?
A HUD-approved housing counselor.
Need a Sounding Board?
If you're weighing whether to keep or sell, call or text me at 951-282-7007. I'll help you understand your home's value and selling options, confidentially.
#MortgageServicer #LoanModification #ForeclosurePrevention #MortgageHelp #HousingCounselor #California #RiversideCounty #Murrieta #Temecula #Homeowners #HBOR
Sources: 12 CFR §§ 1024.35, 1024.36 and 1024.41 (Regulation X); California Civil Code § 2923.7 (single point of contact); Consumer Financial Protection Bureau. Requirements depend on your loan and circumstances. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now