By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
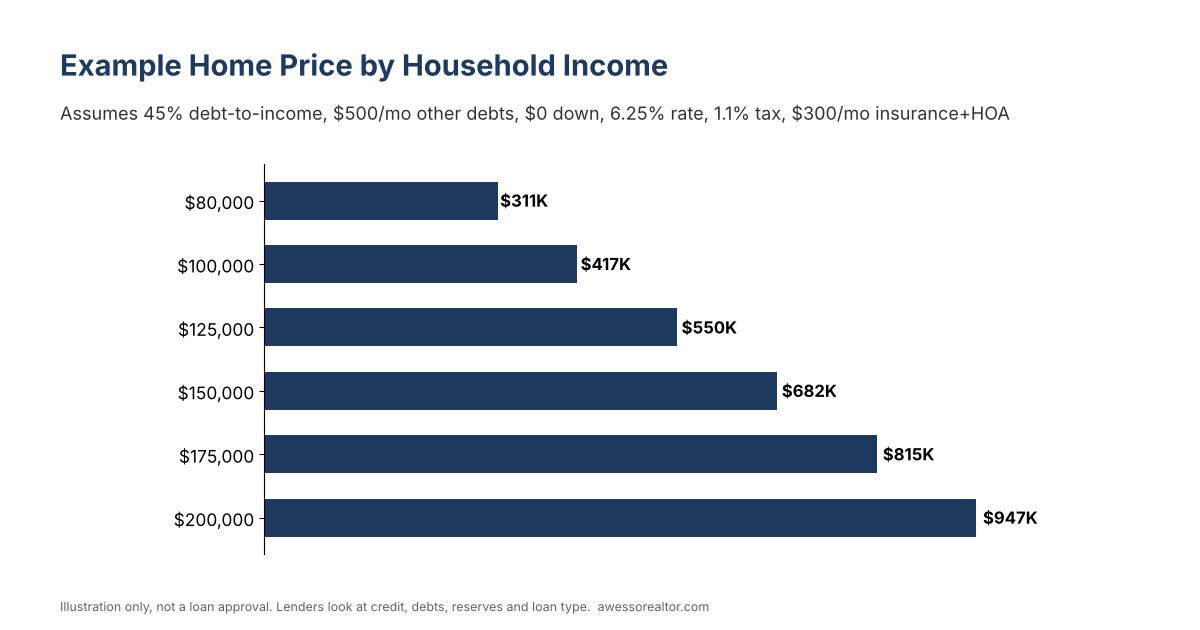
Quick answer: How much house you can afford in Riverside County depends on your income, debts, down payment, interest rate and the home's taxes, insurance and HOA dues. As a rough example, with a $125,000 household income, $500 a month in other debts, no down payment and a 6.25% rate, a lender using a 45% debt-to-income limit might approve a home around $550,000. Mello-Roos, HOA dues and insurance can lower that number, so always compare the full monthly payment.
How Lenders Decide What You Can Afford
Lenders look mainly at your debt-to-income ratio (DTI): your monthly debts, including the new house payment, divided by your gross monthly income. Many loans allow a total DTI in the 43% to 50% range, depending on the loan type, your credit and your savings. The house payment includes:
- Principal and interest on the loan
- Property tax: California's base rate is 1% of the purchase price plus local voter-approved charges, often about 1.1% or more
- Mello-Roos special taxes in many newer communities
- Homeowners insurance
- HOA dues
- Mortgage insurance on many FHA and low-down-payment conventional loans
Example Affordability by Income
The chart above uses these assumptions: 45% total DTI, $500 a month in other debts, $0 down, a 6.25% interest rate, 1.1% property tax, and $300 a month for insurance and HOA dues. It doesn't include Mello-Roos, mortgage insurance or the VA funding fee.
| Household income |
Max total housing payment (example) |
Example home price |
| $80,000 |
About $2,500/month |
About $311,000 |
| $100,000 |
About $3,250/month |
About $417,000 |
| $125,000 |
About $4,190/month |
About $550,000 |
| $150,000 |
About $5,125/month |
About $682,000 |
| $175,000 |
About $6,060/month |
About $815,000 |
| $200,000 |
About $7,000/month |
About $947,000 |
These are illustrations only, not loan approvals. Your real numbers depend on your credit, debts, savings, loan type and today's rates. Try the mortgage calculator or get pre-approved for an exact answer.
What Lowers Your Buying Power
- Mello-Roos: a $300 monthly special tax can reduce your price range by tens of thousands of dollars.
- HOA dues: higher dues mean a lower loan amount for the same payment.
- Car loans and credit card payments: every dollar of monthly debt counts.
- Higher rates: even a half-point change in rate moves your price range.
- Insurance: homes near hills or brush can cost more to insure.
What Raises Your Buying Power
- Paying down monthly debts before you apply
- A larger down payment
- A higher credit score, which can lower your rate
- Choosing a home with low or no Mello-Roos and HOA dues
- Seller credits or a temporary rate buydown, which some builders and sellers offer
- For military buyers, BAH counted as income when you qualify
Where Your Budget Goes Further in Riverside County
Prices vary a lot across the county. In general:
Foreclosures and short sales can also stretch a budget if you can handle repairs. See current foreclosures and bank-owned homes.
Don't Forget Cash to Close
Besides the down payment, plan for closing costs, often about 2% to 5% of the price in California, plus moving costs and a cushion for repairs. VA loans can require no down payment, FHA requires 3.5%, and some conventional loans allow 3%. Down payment assistance may help. Read my first-time buyer guide.
A Quick Way to Estimate Your Own Number
- Multiply your gross monthly income by 0.45.
- Subtract your monthly debt payments (car, cards, student loans).
- The result is roughly the most a lender may allow for your total house payment.
- Decide what you're comfortable paying. The lender's maximum isn't always your best budget.
How Interest Rates Change Your Buying Power
Here's the same $3,500 monthly principal-and-interest budget at three rates on a 30-year loan:
| Interest rate |
Loan amount the payment covers |
| 5.50% |
About $616,000 |
| 6.25% |
About $568,000 |
| 7.00% |
About $526,000 |
That's a swing of about $90,000 between 5.5% and 7%. A temporary rate buydown or a lower rate from better credit can make a real difference.
How Loan Type Affects Affordability
- VA: no monthly mortgage insurance, which leaves more room for the loan itself.
- FHA: flexible credit, but monthly mortgage insurance reduces buying power slightly.
- Conventional: mortgage insurance with less than 20% down, but it can be removed later.
- Down payment assistance: can lower your cash to close, but some programs add a second loan payment or a share of appreciation.
Rent vs. Buy: A Quick Check
Compare your current rent with the full monthly cost of owning a similar home: mortgage, taxes, Mello-Roos, insurance, HOA dues and about 1% of the home's value per year for maintenance. Then think about how long you'll stay. Buying usually makes more sense the longer you stay, because closing costs are spread over more years and you build equity with each payment.
Military Buyers: Using BAH
Lenders generally count BAH as income, and your BAH is set by your duty station and pay grade, not by where you live. That means you can compare homes in Temecula, Murrieta and Menifee on the same BAH. See my guides to buying near Camp Pendleton and March Air Reserve Base.
Related Guides
Frequently Asked Questions
How much house can I afford on $100,000 a year in Riverside County?
Using the example assumptions above, roughly $400,000 to $420,000, but it depends on your debts, down payment, rate and the home's taxes and dues. A pre-approval gives you a real number.
What debt-to-income ratio do lenders allow?
Many loans allow a total DTI in the 43% to 50% range depending on the loan type, credit and reserves. Some VA and FHA loans can go higher with strong compensating factors.
Does Mello-Roos affect how much I can afford?
Yes. Lenders count Mello-Roos as part of your housing payment, so homes with higher special taxes reduce your maximum price.
Can I count BAH as income?
Yes. Lenders generally count Basic Allowance for Housing as income for military borrowers.
Get Your Real Number
I'm a Realtor® and U.S. Navy veteran in Murrieta. I'll help you find homes that fit your budget, not just your approval. Call or text 951-282-7007 or apply for a home loan.
#HowMuchHouseCanIAfford #HomeAffordability #RiversideCounty #Murrieta #Temecula #Menifee #FirstTimeHomeBuyer #VALoan #MortgageTips #InlandEmpire #HomeBuying
Sources: Consumer Financial Protection Bureau; California State Board of Equalization (property tax basics); U.S. Department of Veterans Affairs. The examples are illustrations, not loan quotes or approvals. Rates, guidelines and costs change. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now