By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: You can buy a foreclosure in Riverside County three main ways: as a bank-owned (REO) home listed by an agent, at a trustee sale auction, or before foreclosure through a short sale or pre-foreclosure. Bank-owned homes are the easiest for most buyers because you can inspect and use a loan. Auctions usually require cash and no inspection, so they carry more risk. Get pre-approved, set a repair budget, and work with an agent who knows bank contracts.
Why Foreclosures Are Back in the News
Foreclosure activity has been rising in 2026 compared with the year before, according to ATTOM, a national property data firm. Bank repossessions jumped sharply in early 2026. That said, foreclosures are rising from historically low levels, and most homeowners still have equity. For buyers, it means more distressed listings to choose from than in recent years, not a 2008-style flood.
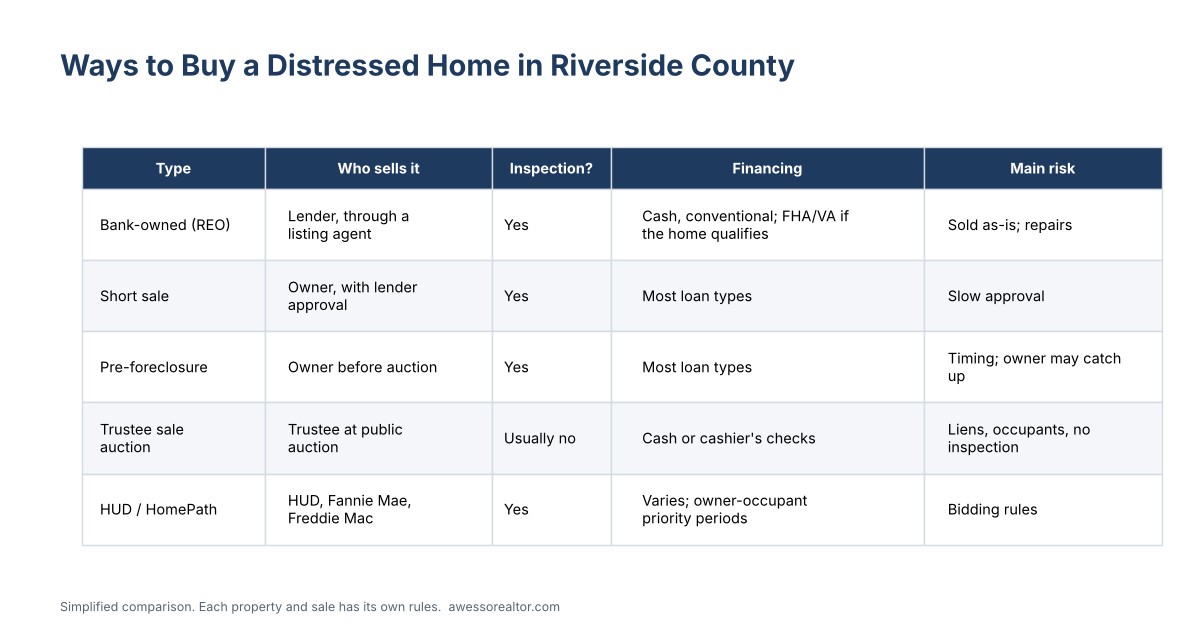
Option 1: Bank-Owned (REO) Homes
When a home does not sell at the trustee sale auction, ownership goes to the lender. The lender then hires a listing agent and sells it on the MLS as a real estate owned (REO) property. This is the most common way regular buyers purchase foreclosures.
- Pros: you can tour and inspect the home, use financing, and get title insurance.
- Cons: sold as-is, banks use their own addenda that override parts of the standard contract, and responses can be slower.
See current foreclosures and bank-owned homes in Riverside County.
Option 2: Short Sales
In a short sale, the owner sells for less than the loan balance, and the lender must approve the deal. Short sales often need more patience, because lender approval can take weeks or longer. They can be a good fit if you are flexible on timing.
Option 3: Pre-Foreclosures
Pre-foreclosure homes belong to owners who are behind on payments but have not lost the home yet. Some list their home for sale to avoid foreclosure. The owner may still catch up on payments and cancel the sale, so timing is uncertain.
Option 4: Trustee Sale Auctions
California foreclosures are usually nonjudicial, which means the home is sold at a public trustee sale instead of through court. Auctions are the riskiest way to buy:
- You usually must pay with cash or cashier's checks.
- You usually cannot inspect the inside.
- Some liens, such as certain tax liens, may survive the sale.
- The home may still be occupied, and you are responsible for possession.
- For 1–4 unit homes, California law can give certain eligible bidders a short window after the auction to submit a bid, so a sale may not be final right away.
Research title, liens and the property before you bid, and consider talking to a real estate attorney.
Option 5: HUD Homes and Government-Owned Homes
HUD sells homes from foreclosed FHA loans through HUDHomestore.gov, and Fannie Mae and Freddie Mac sell their foreclosures through programs like HomePath and HomeSteps. Many of these give owner-occupants a priority period before investors can bid. You usually need an agent registered with the program to submit an offer.
How to Finance a Foreclosure
- Cash: required at auctions and strongest for REOs.
- Conventional loans: work if the home is in livable condition.
- FHA and VA loans: possible if the home meets their property standards. Peeling paint, missing appliances or roof problems can be a problem.
- Renovation loans: an FHA 203(k) or similar loan can roll repair costs into the mortgage.
Get pre-approved before you shop. Apply for a home loan.
Inspection and Repair Budget
Foreclosed homes are often vacant, which means water leaks, mold, plumbing issues and missing fixtures can go unnoticed. Always inspect when you can, and budget for:
- Roof, plumbing, electrical and HVAC
- Water damage and mold
- Pool equipment, if there is a pool
- Septic and well systems on rural lots
- Utilities that may be turned off before inspection
How to Make a Winning Offer on an REO
- Get a pre-approval letter or proof of funds ready.
- Price your offer using recent comparable sales and your repair estimate.
- Keep terms clean and timelines realistic.
- Read the bank's addendum carefully before signing.
- Expect counteroffers and respond quickly.
Where to Find Riverside County Foreclosures
Bank-owned and short sale homes appear on the MLS. Auction notices are recorded with the county and published. I set up custom alerts for foreclosures and short sales across Murrieta, Temecula, Menifee, Perris, Lake Elsinore, Hemet, San Jacinto and Moreno Valley so you see new listings fast. Start your foreclosure search.
Is a Foreclosure Right for You?
| Good fit if you... |
Think twice if you... |
| Have a repair budget |
Need a move-in-ready home |
| Can be patient with bank timelines |
Must close by a fixed date |
| Want to build equity through improvements |
Have no savings after your down payment |
| Have cash or a renovation loan |
Plan to use FHA or VA on a home in poor condition |
Step-by-Step: Buying a Bank-Owned Home
- Get pre-approved or gather proof of funds.
- Set up alerts for new REO and short sale listings in your target cities.
- Tour quickly, because good REOs can get multiple offers.
- Estimate repairs using a contractor or inspector if possible.
- Write your offer based on comparable sales minus repair costs.
- Review the bank's addendum, which often limits seller repairs and disclosures and sets per-day penalties for late closing.
- Inspect within your contingency period and decide whether to proceed.
- Close escrow, then change the locks and start repairs.
Researching a Property Before a Trustee Sale
- Read the Notice of Trustee Sale for the sale date, location and opening bid.
- Order a title report or work with a title company to identify liens.
- Check property tax status with the Riverside County Treasurer-Tax Collector.
- Look up permits and code violations with the city or county.
- Drive by to check the exterior and whether the home appears occupied.
- Confirm the sale hasn't been postponed or canceled the day before and the morning of the sale.
Costs to Expect Beyond the Price
| Cost |
Notes |
| Repairs and rehab |
Often the biggest variable. Get bids early. |
| Inspections |
General, roof, sewer line, pool and septic if needed. |
| Utilities turn-on |
Banks may require you to arrange this for inspection. |
| Back HOA dues or liens |
Check whether the seller or buyer pays them in the contract. |
| Possession costs |
For occupied auction homes, eviction or cash-for-keys. |
| Holding costs |
Mortgage, taxes, insurance and utilities during repairs. |
Foreclosure vs. Short Sale: Which Should You Buy?
A bank-owned home is usually faster and more predictable once the bank responds, but it's sold as-is. A short sale may be in better condition because the owner still lives there, but the lender's approval can take much longer and the deal can fall apart. If you need to move by a fixed date, an REO is usually the safer choice. If you're flexible and want a better-kept home, a short sale can be worth the wait.
Investor vs. Owner-Occupant
Owner-occupants often get priority on government-owned homes, can use low-down-payment loans, and may qualify for renovation financing. Investors usually need larger down payments or cash, but can move faster at auctions. Be honest about occupancy on any program or loan application.
Related Guides
Frequently Asked Questions
Can I get a loan to buy a foreclosure?
Yes for most bank-owned homes and short sales, as long as the property meets the loan's condition standards. Auctions usually require cash.
Are foreclosures really cheaper?
Often, but not always. Banks price REOs using market data, and repair costs can erase the discount. Compare the price plus repairs with similar homes in good condition.
What are the risks of buying a foreclosure?
Hidden repairs, as-is condition, slow bank responses, and at auctions, liens, occupants and no inspection. An experienced agent and a thorough inspection reduce the risk.
Can I use a VA loan on a foreclosure?
Yes, if the home meets VA minimum property requirements. Homes that need major repairs may not qualify until those repairs are made.
Ready to Find a Foreclosure Deal?
I'm a Realtor® and U.S. Navy veteran who helps buyers and investors find and buy distressed homes in Riverside County. Call or text 951-282-7007 or see current foreclosures.
#Foreclosures #BankOwnedHomes #REO #ShortSale #RiversideCounty #MurrietaRealEstate #TemeculaRealEstate #InlandEmpire #RealEstateInvesting #FixerUpper #HomeBuying
Sources: ATTOM Q1 2026 foreclosure report; U.S. Department of Housing and Urban Development; California Civil Code §§ 2924–2924m. Auction and bidding rules are complex and change. This article is general information, not legal, tax or financial advice. Consult a real estate attorney before bidding at a trustee sale.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now