By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
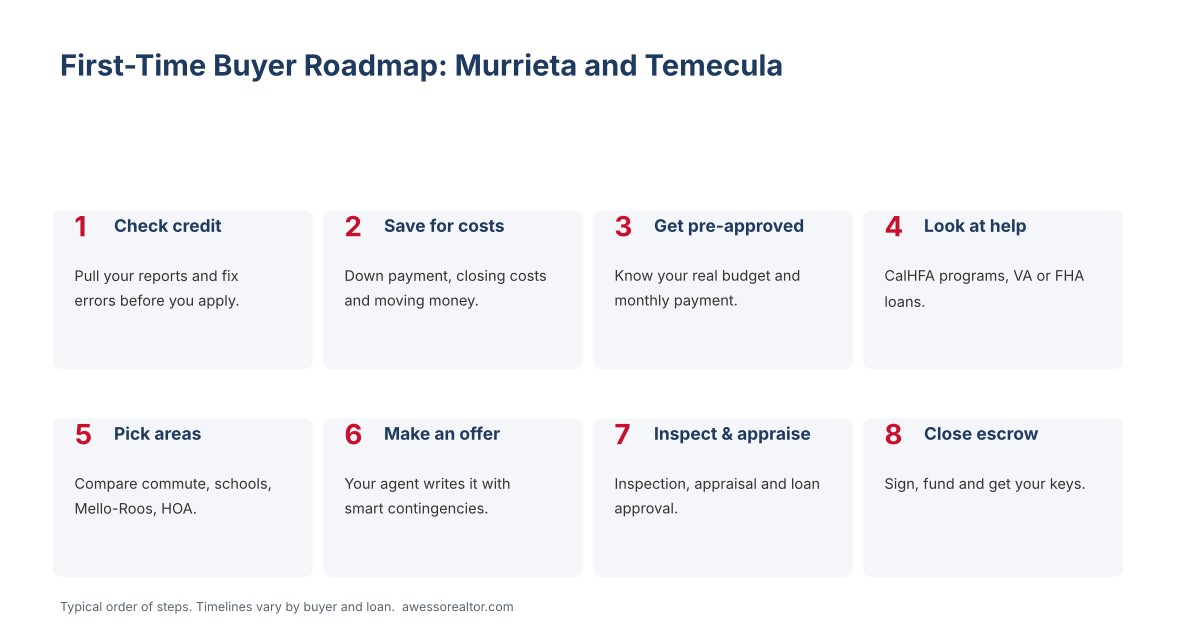
Quick answer: To buy your first home in Murrieta or Temecula, check your credit, save for your down payment and closing costs, get pre-approved, and look at help like CalHFA programs, FHA (3.5% down) or VA (often $0 down) loans. Then choose your area, make an offer with smart contingencies, and close escrow in about 30 to 45 days. Budget for Mello-Roos and HOA dues, which are common in newer neighborhoods.
Step 1: Check Your Credit
Start by pulling your free credit reports at AnnualCreditReport.com and disputing any errors. Your credit score affects which loans you qualify for and your interest rate. FHA loans can allow lower scores than conventional loans, but a higher score usually means a lower rate and lower monthly payment. Pay bills on time and avoid new credit cards or car loans while you shop for a home.
Step 2: Save for the Costs of Buying
You will need money for three things:
- Down payment: as little as 0% with a VA loan, 3.5% with FHA, or about 3% with some conventional first-time buyer loans.
- Closing costs: lender fees, escrow, title insurance, prepaid taxes and insurance. In California these often run about 2% to 5% of the price, and sellers or lenders sometimes help pay them.
- Earnest money deposit: often around 1% to 3% of the price, which goes into escrow when your offer is accepted and counts toward your costs at closing.
Keep extra savings for moving, furniture and repairs after you move in.
Step 3: Get Pre-Approved
A pre-approval tells you how much you can borrow and shows sellers you are serious. The lender reviews your income, debts, credit and savings. Bring recent pay stubs, W-2s or tax returns, bank statements and photo ID. In competitive neighborhoods, sellers often will not look at an offer without one. Start your pre-approval here, or read how much house you can afford in Riverside County.
Step 4: Look for Down Payment Help
First-time buyers in Riverside County have several options to look into:
- CalHFA programs. The California Housing Finance Agency offers first mortgages and down payment assistance. Its California Dream For All shared appreciation loan can cover up to 20% of the price (capped at $150,000), but you repay it plus a share of the home's appreciation when you sell or refinance. CalHFA says the 2026 application period closed in March 2026, so watch for future rounds. CalHFA's MyHome Assistance program is another option to ask a CalHFA-approved lender about.
- FHA loans. 3.5% down with flexible credit guidelines, plus mortgage insurance.
- VA loans. For eligible service members and veterans, often with no down payment and no monthly mortgage insurance.
- Conventional first-time buyer loans. Some allow 3% down. Private mortgage insurance can be removed later.
- Local programs. Riverside County and some cities offer first-time buyer help from time to time, with income limits.
Most programs have income limits and require a homebuyer education class. Program rules and funding change, so confirm current details with CalHFA or your lender.
Step 5: Choose Where to Buy
Murrieta and Temecula sit side by side but feel different. Temecula is known for wine country and Old Town, and usually costs more. Murrieta has many family neighborhoods and sits where I-15 and I-215 meet. If your budget is tight, also look at Menifee, Lake Elsinore or Perris.
For each home, compare:
- Commute at rush hour
- School assignment for the exact address
- Mello-Roos special taxes and HOA dues
- Insurance cost, especially near hills and brush
- Age of the roof, air conditioning and water heater
Step 6: Make an Offer
Since 2024, buyers sign a written agreement with their agent before touring homes, which explains what the agent does and how they are paid. When you find the right home, your agent writes an offer on the California Residential Purchase Agreement. Key terms include price, deposit, closing date, who pays which costs, and contingencies. Contingencies let you cancel and keep your deposit if the inspection, appraisal or loan approval falls through within set time periods, often 17 days in the standard form unless you change them. Talk with your agent before shortening or removing any contingency.
Step 7: Inspection, Appraisal and Loan Approval
Hire a home inspector right away. Read the report and ask questions. You can ask the seller for repairs or a credit, or cancel within your contingency period. Your lender orders an appraisal to confirm the home's value. If it comes in low, you can renegotiate, pay the difference or cancel within your appraisal contingency. Avoid new debt or job changes until closing.
Step 8: Close Escrow and Get Your Keys
A typical escrow in California takes about 30 to 45 days. Before closing, you will do a final walkthrough, review your Closing Disclosure and sign loan documents. Never wire money based on an email alone. Call your escrow officer at a known number to confirm wiring instructions, because wire fraud scams target home buyers.
First-Time Buyer Budget Checklist
| Cost |
When you pay it |
Tip |
| Earnest money deposit |
Within days of acceptance |
Credited back to you at closing |
| Home inspection |
During escrow |
Add a roof or sewer inspection if needed |
| Appraisal |
During escrow |
Ordered by your lender |
| Down payment |
At closing |
0% VA, 3.5% FHA, about 3% some conventional |
| Closing costs |
At closing |
Ask about seller or lender credits |
| Moving and setup |
After closing |
Keep a repair cushion |
Mistakes First-Time Buyers Make
- Shopping before getting pre-approved.
- Looking only at price instead of the full monthly payment with Mello-Roos and HOA.
- Skipping the inspection on a newer home.
- Opening new credit or changing jobs during escrow.
- Draining all savings for the down payment with nothing left for repairs.
Which Loan Is Right for a First-Time Buyer?
| Loan |
Down payment |
Mortgage insurance |
Good fit for |
| FHA |
3.5% |
Yes, upfront and monthly |
Lower credit scores, smaller savings |
| VA |
Often $0 |
No monthly insurance; funding fee unless exempt |
Eligible service members and veterans |
| Conventional (first-time buyer programs) |
About 3% |
Yes until about 20% equity, then removable |
Good credit, steady income |
| CalHFA programs |
Varies; assistance available |
Depends on first mortgage |
Income-qualified first-time buyers |
Questions to Ask Your Lender
- Which loan types do I qualify for, and how do the monthly payments compare?
- What will my estimated cash to close be?
- Do I qualify for any down payment assistance?
- How long is my rate lock, and what happens if escrow runs longer?
- What should I avoid doing before closing?
Ask for a Loan Estimate for each option. It's a standard form that makes it easy to compare costs side by side. Start here.
New Construction vs. Resale for First-Time Buyers
Builders in Murrieta, Menifee and French Valley often offer incentives like closing cost help or rate buydowns. New homes need fewer repairs, but often come with higher Mello-Roos taxes and HOA dues. Resale homes may have lower monthly taxes and mature landscaping but need more maintenance. Bring your own agent on your first visit to a builder's sales office, because the builder's sales team works for the builder.
Related Guides
Frequently Asked Questions
How much do I need to save to buy my first home?
It depends on your loan. VA loans can require no down payment, FHA requires 3.5%, and some conventional loans allow 3%. Plan for closing costs of about 2% to 5% of the price, plus moving and repair money.
How long does it take to buy a house in Murrieta or Temecula?
Many buyers take one to three months to find a home, then about 30 to 45 days in escrow. Getting pre-approved first speeds everything up.
What mistakes should first-time buyers avoid?
Don't shop before pre-approval, don't ignore Mello-Roos and HOA costs, don't skip the inspection, and don't take on new debt before closing.
Who counts as a first-time home buyer?
Many programs define a first-time buyer as someone who has not owned a home in the past three years, but each program sets its own rules.
Ready to Buy Your First Home?
I'm a Realtor® and U.S. Navy veteran based in Murrieta. I'll walk you through every step, from pre-approval to keys. Call or text 951-282-7007, apply for a home loan, or search homes for sale.
#FirstTimeHomeBuyer #Murrieta #Temecula #MurrietaRealEstate #TemeculaRealEstate #CalHFA #FHALoan #VALoan #HomeBuyingTips #RiversideCounty #InlandEmpireHomes
Sources: CalHFA, California Dream For All; U.S. Department of Housing and Urban Development (FHA); U.S. Department of Veterans Affairs; Consumer Financial Protection Bureau. Programs, limits and funding change, so confirm current details with the agency or your lender. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now