By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: CalHFA, the California Housing Finance Agency, offers 30-year fixed first mortgages (CalHFA FHA and CalHFA Conventional) through approved lenders, plus help with the down payment and closing costs. Its MyHome Assistance loan covers up to 3.5% (FHA) or 3% (conventional) and is deferred until you sell, refinance or pay off the loan. CalHFA programs are for first-time buyers within county income limits, and at least one buyer must complete homebuyer education.
What Is CalHFA?
CalHFA is California's state housing finance agency. It doesn't lend directly to the public. Instead, it works through approved private lenders who originate CalHFA loans. That means you apply with a CalHFA-approved loan officer, not with the state.
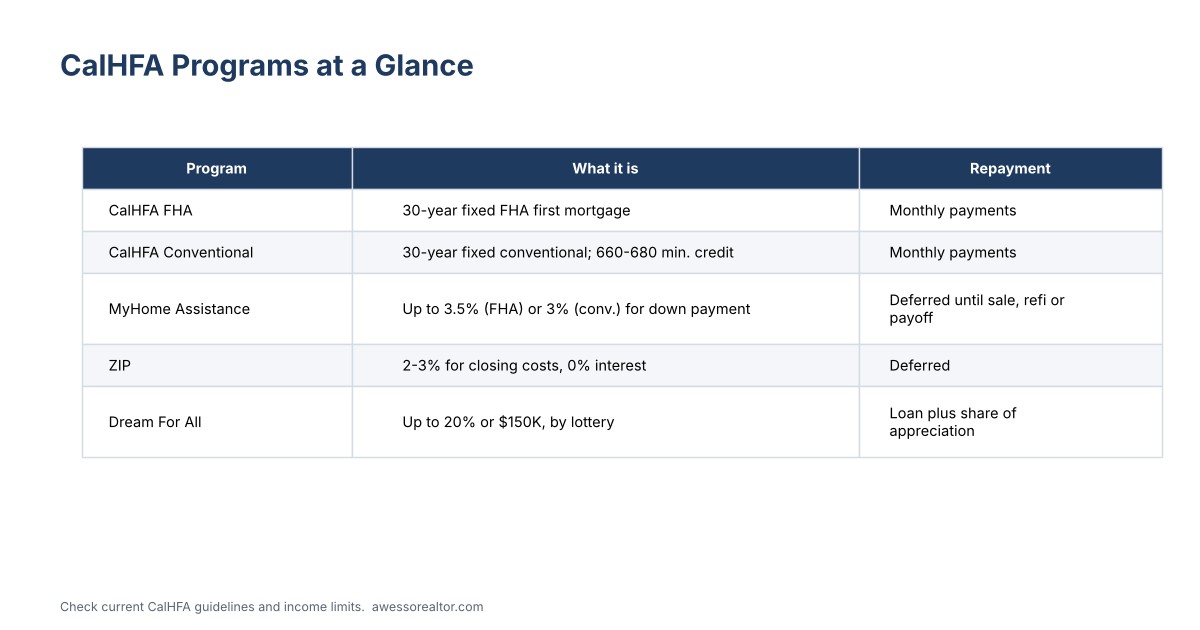
CalHFA First Mortgages
CalHFA FHA
An FHA-insured 30-year fixed loan. It follows FHA rules, including FHA mortgage insurance and property standards, with CalHFA's own overlays. It works well for buyers with moderate credit who need flexible guidelines.
CalHFA Conventional
A conventional 30-year fixed loan. Under CalHFA's 2026 handbook, it generally requires a minimum credit score of 660 or 680 depending on income, and a debt-to-income ratio up to 45% or 50% depending on credit score. Mortgage insurance may be reduced for lower-income borrowers.
CalHFA Down Payment and Closing Cost Help
| Program |
Amount |
How it's repaid |
| MyHome Assistance |
Up to 3.5% (FHA) or 3% (conventional) |
Deferred until sale, refinance or payoff |
| Zero Interest Program (ZIP) |
2% or 3% of the first loan, closing costs only |
0% interest, deferred; available with CalPLUS Conventional |
| Dream For All (when open) |
Up to 20% or $150,000 |
Repay the loan plus a share of appreciation |
Dream For All is awarded by lottery during short windows. The 2026 round ran February 24 to March 16 and required at least one first-generation buyer.
Who Qualifies for CalHFA?
- First-time buyers: generally, no ownership interest in a principal residence in the past three years. Required when you use CalHFA down payment help.
- Income limits: set by county. Check CalHFA's current income limits for Riverside or San Diego County.
- Owner-occupancy: you must live in the home as your primary residence.
- Homebuyer education: one first-time borrower must complete an approved course, such as the eHome online course or a HUD-approved counselor.
- Property: one-unit homes, including approved condos and PUDs; manufactured homes are allowed in some cases.
Example: How CalHFA Can Lower Your Cash to Close
On a $500,000 home with a CalHFA FHA loan:
- FHA down payment of 3.5%: $17,500
- MyHome Assistance of up to 3.5%: up to $17,500, which can cover the down payment
- You'd still budget for closing costs and reserves, unless the seller or other programs help
This is an illustration only. Your lender will confirm the actual amounts. Try the mortgage calculator to see payments.
Pros and Cons of CalHFA Loans
| Pros |
Cons |
| Little or no cash needed for the down payment |
Interest rates can be higher than a standard loan |
| Deferred second loans with no monthly payment |
Second loans must be repaid when you sell or refinance |
| 30-year fixed rate |
Income limits and first-time buyer rules |
| Can combine with some local programs |
Extra paperwork can add time to close |
CalHFA vs. Other Options
- VA loan: if you're eligible, a VA loan with no down payment may cost less than a CalHFA loan.
- County DPA: Riverside County's PLHA program offers up to 20% (capped at $100,000) in eligible cities. See down payment assistance in Riverside County.
- Standard FHA or conventional: may have a lower rate if you have savings for the down payment.
How to Get a CalHFA Loan
- Check CalHFA income limits for the county where you'll buy.
- Complete homebuyer education.
- Get pre-approved with a CalHFA-approved lender. Start your application.
- Shop for a home that meets the program's property rules.
- Your lender reserves CalHFA funds once you're in contract.
- Close escrow, usually in 30 to 45 days.
Common Questions to Ask Your Lender
- What's the rate difference between CalHFA and a standard loan?
- Can I combine MyHome with a county or city program?
- How much will I owe on the second loan if I sell in five years?
- Is my income under the limit for my county?
CalHFA Income Limits
CalHFA sets separate income limits for its first mortgages and its down payment programs, and they vary by county and household size. Riverside and San Diego counties have different limits, and the limits are updated periodically. Check CalHFA's current income limit chart for the county where you're buying, or ask a CalHFA-approved lender to run the numbers with your household income.
Mistakes to Avoid With CalHFA
- Assuming the down payment help is a grant. MyHome and ZIP are loans repaid later.
- Not comparing the CalHFA rate with a standard loan and a VA loan, if you're eligible.
- Waiting to take homebuyer education until you're in escrow.
- Choosing a condo that doesn't meet the first mortgage's guidelines.
How Long Does It Take to Save Without Help?
Saving 3.5% plus closing costs on a $500,000 home means roughly $29,000 or more. At $750 a month, that's more than three years. CalHFA and county programs can shorten that wait significantly, which is why many first-time buyers in Murrieta and Temecula use them.
Related Guides
Frequently Asked Questions
What credit score do I need for a CalHFA loan?
For CalHFA Conventional, generally 660 or 680 depending on income. CalHFA FHA requirements can differ, so ask a CalHFA-approved lender.
Do I have to pay back MyHome Assistance?
Yes. It's a deferred loan, repaid when you sell, refinance or pay off your first mortgage.
Can I use CalHFA if I've owned a home before?
For the down payment help, you generally can't have owned a principal residence in the past three years.
How long does a CalHFA loan take?
Usually 30 to 45 days, sometimes longer when combined with other assistance programs.
Ready to See If You Qualify?
I'm a Realtor® and U.S. Navy veteran who helps first-time buyers in Murrieta, Temecula and the Inland Empire use CalHFA and other programs. Call or text 951-282-7007 or apply for a home loan.
#CalHFA #FirstTimeHomeBuyer #DownPaymentAssistance #MyHomeAssistance #DreamForAll #CaliforniaHomeBuyer #Murrieta #Temecula #RiversideCounty #FHA #HomeLoan
Sources: CalHFA MyHome Assistance; CalHFA Conventional Program Handbook (May 2026); CalHFA Dream For All 2026 announcement. Rates, credit requirements, income limits and program availability change. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now