By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
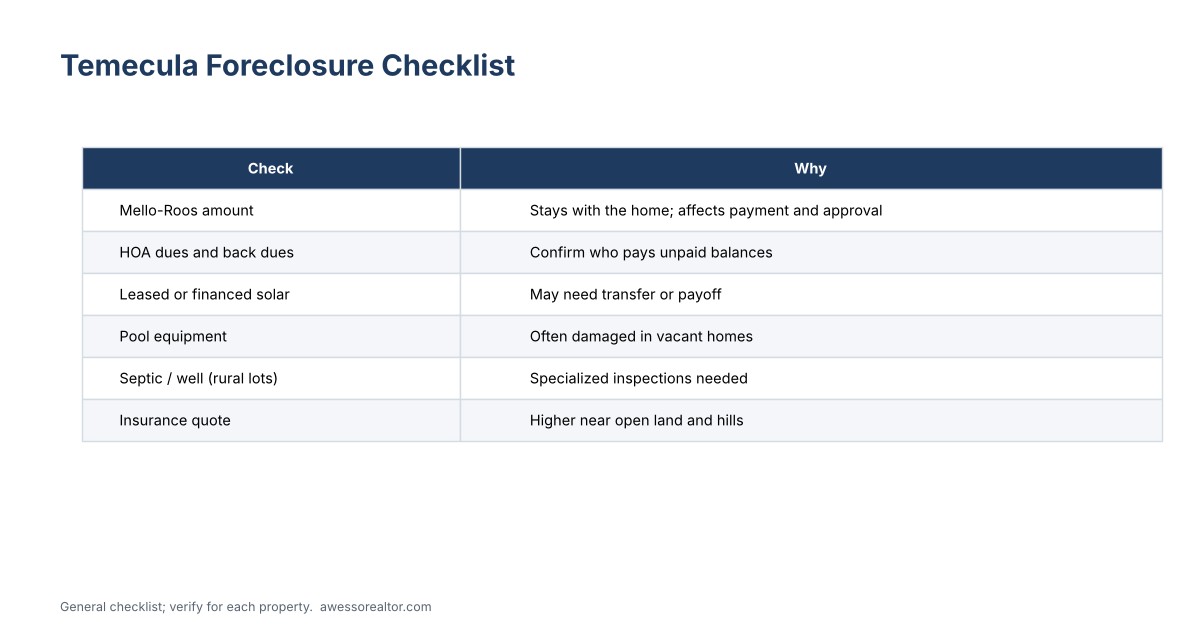
Quick answer: Temecula foreclosures are uncommon compared with cheaper parts of Riverside County, so the ones that do hit the market move fast. Find them through MLS alerts for bank-owned (REO) and short sale listings, HUD and Fannie Mae HomePath, and recorded trustee sale notices if you're a cash investor. Before you offer, check the home's Mello-Roos and HOA dues, any leased solar, and septic or well systems on wine country properties, because those costs stay with the house after foreclosure.
What the Temecula Foreclosure Market Looks Like
Temecula has higher prices and more owner equity than many Inland Empire cities, so most struggling owners can sell before foreclosure. That means fewer bank-owned homes, more short sales and equity sales, and strong competition for anything priced well. ATTOM reports that foreclosure activity rose in 2026 compared with 2025, but it's still low by historical standards. Expect a handful of distressed listings at a time, not dozens. See current Temecula-area foreclosures and bank-owned homes.
Where Temecula Distressed Homes Show Up
- Newer planned communities like Wolf Creek, Harveston and Paloma del Sol, where higher Mello-Roos and HOA dues can stretch owners who bought recently.
- Condos and townhomes near the Promenade and Old Town, which can be more sensitive to HOA increases and special assessments.
- Wine country and rural estates, which are rarer but can come with wells, septic systems, larger repair bills and higher insurance.
- Older neighborhoods in central Temecula and Vail Ranch with dated systems that scare off some buyers.
Learn the areas in best neighborhoods in Temecula for families.
Five Ways to Find Temecula Foreclosures
- MLS alerts for REO, short sale and "court-approved" listings in Temecula, Murrieta, French Valley and Fallbrook. I set these up so you see new listings the day they post.
- HUD homes on HUDHomestore.gov, often with an owner-occupant priority period.
- Fannie Mae HomePath and Freddie Mac HomeSteps listings.
- Trustee sale notices recorded with the Riverside County Recorder, for experienced cash buyers.
- Pre-foreclosure owners who list their homes to avoid foreclosure. Approach them respectfully and follow California's rules on buying from homeowners in foreclosure.
Temecula-Specific Things to Check Before You Offer
| Item |
Why it matters |
| Mello-Roos (special taxes) |
Stays with the property and affects your monthly payment and loan approval |
| HOA dues and back dues |
Check the title report and contract for who pays any unpaid balance |
| Leased solar panels |
A lease or loan on the panels may need to be transferred, paid off or removed |
| Pool equipment |
Vacant homes often have damaged pumps, heaters and surfaces |
| Septic and well (rural lots) |
Need specialized inspections and can be expensive to fix |
| Fire risk and insurance |
Homes near open land can be harder and costlier to insure |
Financing a Temecula Foreclosure
- Conventional loans work well for homes that need cosmetic work.
- VA and FHA loans work if the home meets their property standards. Many Camp Pendleton families buy in Temecula with VA loans.
- Renovation loans like FHA 203(k) or Fannie Mae HomeStyle can roll repair costs into the mortgage.
- Cash is required at trustee auctions and is strongest on REOs.
Get pre-approved before you shop so you can move quickly.
Are Temecula Foreclosures a Good Deal?
Sometimes. Because demand for Temecula homes is strong, banks often price REOs close to market and still get multiple offers. The best opportunities tend to be homes with visible but fixable problems: dated interiors, dead landscaping, a tired pool or deferred paint. Compare the price plus repairs with recent sales of updated homes in the same neighborhood, and remember Mello-Roos when you compare monthly costs.
Step-by-Step: Buying a Temecula Bank-Owned Home
- Get pre-approved or gather proof of funds.
- Set up REO and short sale alerts.
- Tour fast; bring a contractor or get bids.
- Check Mello-Roos, HOA and solar details.
- Write a clean offer based on comps minus repairs.
- Review the bank's addendum. See how the REO buying process works.
- Inspect, including pool, roof and sewer line or septic.
- Close escrow and change the locks.
Short Sales in Temecula
Because many Temecula owners still have some equity, short sales here often involve recent buyers or homes with second loans. They can be in better condition than REOs, but lender approval can take weeks or months. If you need to move by a firm date, an REO or regular listing may be a better fit.
Behind on Your Temecula Mortgage?
If you own in Temecula and you're struggling, you likely have more options than you think, including selling while you still have equity. Read what happens after a missed payment in California.
Costs to Budget Beyond the Price
| Cost |
Notes |
| Inspections |
General, roof, pool, sewer line or septic, termite |
| Utility turn-on |
Banks may require the buyer to arrange it for inspections |
| Immediate repairs |
Items your lender or insurer requires |
| Holding costs |
Loan, taxes, Mello-Roos, HOA and utilities during repairs |
| Solar payoff or transfer |
If the panels are leased or financed |
Mistakes to Avoid
- Comparing only list prices and ignoring Mello-Roos and HOA dues.
- Skipping the pool and septic inspections on vacant homes.
- Signing the bank addendum without reading the per-diem and deposit terms.
- Assuming an FHA or VA loan will work on a home with major damage.
- Bidding at a trustee sale without a title search.
A careful buyer who prepares can still find good value in Temecula, even with fewer distressed listings than nearby cities.
Related Guides
Frequently Asked Questions
Are there many foreclosures in Temecula?
Not many compared with lower-priced cities. Most Temecula owners have equity, so distressed homes appear in small numbers and sell quickly.
Can I get a loan for a Temecula foreclosure?
Yes, for most bank-owned homes and short sales that meet the loan's condition standards. Auctions usually require cash.
Is it really cheaper?
Sometimes. Compare the price plus repairs and monthly Mello-Roos and HOA costs with similar updated homes nearby.
What are the risks?
Hidden repairs, as-is terms, back HOA dues, leased solar, and bank delays. A full inspection and title review reduce the risk.
Get Temecula Foreclosure Alerts
I'm a Realtor® and U.S. Navy veteran serving Temecula and Murrieta. I'll send you new bank-owned and short sale listings as they hit the market. Call or text 951-282-7007 or see current listings.
#TemeculaForeclosures #Temecula #BankOwnedHomes #REO #ShortSale #TemeculaRealEstate #Foreclosures #RiversideCounty #FixerUpper #VALoan #HomeBuying
Sources: ATTOM 2026 mid-year foreclosure report; U.S. Department of Housing and Urban Development; Fannie Mae HomePath; Riverside County Assessor-County Clerk-Recorder; California Civil Code §§ 1695 and 2924–2924m. This article is general information, not legal, tax or financial advice. Consult a real estate attorney before bidding at a trustee sale.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now